Collectively, governments, businesses and households must prioritize a rapid transition to more sustainable forms of energy, unlocking myriad benefits such as lower CO2 emissions, cleaner air and a net-benefit to the global economy.

The global power sector is in the midst of a major transition. In 2024, zero-carbon sources made up 90% of all new power generation capacity additions. The costs of wind and solar power have fallen dramatically over the last decade. The investment shift is already yielding positive impacts: the carbon-intensity of the global power system — the amount of carbon dioxide (CO2) emitted per unit of electricity generated — has fallen by 11% since 2015, although overall emissions by the sector have grown by around 12% in the same time frame due to rising electricity demand.

Accelerating decarbonization in the power sector is fundamental to meeting the ambitions of the Paris Agreement. In fact, strategies for systems such as industry and transport are contingent upon the power system’s decarbonization.
 

Countries need to set ambitious plans to achieve rapid and large-scale deployment of zero-carbon power

National plans to scale zero-carbon electricity generation now exist over most of the globe. At least 160 countries have outlined plans to replace fossil fuel power with lower carbon alternatives. While these commitments are important, they are not being put into practice fast enough.

The share of zero-carbon power in global electricity generation has been steadily increasing since 2011 and stood at 41% as of 2024, but it must accelerate. Collectively, governments, businesses and households must prioritize a rapid transition to more sustainable forms of energy, unlocking myriad benefits such as lower CO2 emissions, cleaner air, more resilient water resources and a net-benefit to the global economy.

Tracking progress on global outcomes

2236: Zero-carbon sources in electricity generation

Status: Well Off Track

Scaling up zero-carbon power sources — such as solar, wind, hydro and nuclear — can reduce carbon dioxide (CO2) emissions and local air pollutants while meeting rising global electricity needs.

The share of zero-carbon sources in global electricity grew to reach 41% in 2024, a continuation of recent trends. Different zero-carbon technologies are on different trajectories. Solar power is in the breakthrough stage of an S-curve, growing exponentially over the past five years, while wind power is in the diffusion stage of an S-curve, having grown exponentially previously but growing linearly over the last five years. Hydropower and nuclear power have remained flat in absolute terms, and thus are losing market share as electricity demand grows.

Assuming that solar and wind follow an S-curve, while nuclear and hydropower continue on a linear trajectory, the share of zero-carbon sources in electricity would get less than half of the way from the current level to the ambitious 1.5 degrees C-aligned target of 88% to 91% in 2030. It is thus considered well off track.

At the country level, progress is mixed. In all of the jurisdictions with the highest emissions from the power sector, zero-carbon power is expanding, though the speed at which this is displacing fossil fuels varies. Since 2019, zero-carbon sources have grown from 61% to 71% of electricity generation in the European Union, from 32% to 38% percent in China, from 38% to 42% percent in the United States and from 21% to 22% percent in India.

2237: Renewables in electricity capacity

Status: Right Direction
S-Curve Trajectory:

Changes are based on the adoption of innovative technologies. These types of technologies often follow an S-curve trajectory in their adoption if they are successful, although this is not guaranteed.

In a zero-carbon power system, the majority of electricity will need to be generated by renewable energy technologies. To measure progress toward this goal, this indicator tracks the share of installed energy capacity that is renewable as a proportion of total installed capacity.

The share of power generation capacity contributed by renewables has been growing rapidly. Since 2012, shares have been increasing by over 3% per year, and estimates from 2022 show 40% of total installed capacity in the power sector is renewable.

Yet, this growth needs to be further accelerated. Zero-carbon power's share of generation should reach 74–92% by 2030 to align with the Paris Agreement, and renewable capacity will need to increase commensurately.

Although renewable energy capacity is growing, additional policies and investments will be required to meet global targets and displace existing fossil fuel electricity generation sources.

2238: Capacity additions of renewable energy

Status: Right Direction
Historical Data Methodology and Challenges:

The global total was calculated by aggregating the values of all technologies. 

To achieve a zero-carbon power system by 2050, nearly all electricity will need to come from renewable technologies. Achieving this will require large-scale renewable energy capacity additions. To track momentum toward this goal, it is critical to monitor annual capacity additions, which represent new installations of renewable power.

Annual capacity additions of renewables are generally increasing. Over the past decade, over 120 gigawatts (GW) of new renewable power capacity have been added each year, with these capacity additions growing at a rate of 11% per year. In 2022 alone, 292 GW of new renewable power was added, driven primarily by the expansion of renewable energy projects in Asia, but also by increasing deployment in Europe and South America. 

In 2021, the capacity additions slowed slightly. Although capacity additions rose in 2022, the small setback in 2021 highlights how major global instabilities such as the COVID-19 pandemic and Russia’s invasion of Ukraine can inhibit progress.

2239: Renewable electricity capacity per capita in developing countries as a fraction of renewable electricity capacity per capita in developed countries

Status: Right Direction
Historical Data Methodology and Challenges:

Total renewable capacity was collected from International Renewable Energy Agency (IRENA) Statistics. The global percentage was calculated by taking the ratio of the total renewable capacity per capita of United Nations Framework Convention on Climate Change (UNFCCC) Non-Annex I countries (developing) by the total renewable capacity per capita of Annex I countries (developed).

Target Methodology:

This indicator focuses on the ratio of renewable electricity capacity per capita in developing countries to that of developed countries (expressed as a percentage) to highlight progress toward reducing inequality among countries.

In 2022, the world had an installed renewable energy capacity of 3.4 terawatts (TW) of renewable electricity, representing an average of 425 watts (W) per person.

But this capacity was not distributed equitably. The average installed renewable energy capacity per capita in developing countries is just over a quarter of that installed in developed countries. This inequity is even more stark for the least developed countries.

This indicator serves as a proxy to capture the unequal benefits of renewables in developed and developing nations. While installed capacity per capita in developing countries has been growing around 10% per year in recent years, there is still a long way to go until parity is reached.

Currently, there are no agreed-upon targets for renewable energy capacity per capita for 2030 and 2050. If developing and developed nations benefited equally from renewables, this indicator would reach 100%, meaning that the installed capacity per capita was equal in developed and developing countries.

Key enablers and barriers to change

2150: Countries with regulatory frameworks for renewable electricity generation

Historical Data Methodology and Challenges:

Data was collected by selecting countries with an overall renewable energy score of >67, in accordance with Regulatory Indicators for Sustainable Energy (RISE). The methodologies for the RISE framework can be found here.

Increasing renewable energy deployment requires transforming regulatory practices. Globally, energy markets and regulators have historically depended on large decentralized power assets, such as coal or gas power plants.

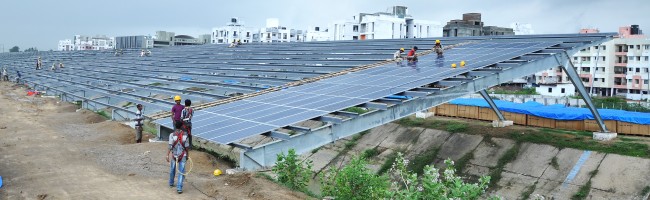
A diverse set of distributed power assets is beginning to enter utility portfolios and energy markets, as well as decentralized renewable energy assets. These range from large onshore wind farms to small-scale rooftop photovoltaic (PV) solar panels on homes.

To encourage the diversification of power supply, regulatory frameworks need to change to allow new technologies, market entrants or distributed generation assets to participate and compete within the electricity market.

This indicator tracks the number of countries with national regulatory frameworks that have tailored rules to incentivize increased renewable power generation.

Analysis of data shows that momentum is slowly moving in the right direction. As of 2023, conducive regulatory frameworks were in place in eight countries, an increase from one country in 2015. This data does not speak to the quality of these regulations.

2151: Countries with tax incentives for renewable electricity generation

Historical Data Methodology and Challenges:

Data was collected from the International Energy Agency (IEA) Policy Database by selecting countries with national renewable tax incentives that are in force. The list of tax incentives might not be comprehensive, given that there is no database that collects primary data on this indicator.

Tax incentives for renewable electricity generation help renewable generators become economically competitive with existing power plant assets that often have benefited from years of government subsidies.

Renewable incentives come in many different shapes and forms, such as removing value-added tax on renewable energy equipment or reducing corporate taxes for renewable energy companies. Tax incentives for renewable energy generation are a win-win: they increase profit margins for sustainable energy companies and reduce costs for consumers, thus promoting the development of the sector.

This indicator tracks countries offering tax incentives for the clean energy sector. Analysis of 2022 data shows that 53 countries had tax incentives for renewable energy in force. Due to data and time limitations, we do not yet delve into the quality of these tax benefits, but this may be addressed in a future release of this platform.

2152: Countries with renewable energy targets

Historical Data Methodology and Challenges:

The number of countries with quantified targets that focus on power was collected from IRENA’s annual NDC reports.

National-level targets set a clear and ambitious course for increasing renewable energy generation over time. They send a strong signal to the economy for a future energy shift.

Targets can galvanize societal change, influencing energy sector decision-makers and investors. By emphasizing renewable energy technologies rather than fossil fuels, they help avoid the risk of overinvestment in fossil fuel power sources and their associated carbon.

The latest estimates show that renewable energy targets now cover most of the globe: as of 2023, there were 113 countries with quantified renewable energy targets in their NDCs that focus on power.

We do not yet explore the quality of these targets in relation to the Paris Agreement, which is a critical component that may be explored in future analyses. A sufficient renewable energy target should be ambitious enough to achieve deep decarbonization at the speed necessary and backed by clear policy and implementation strategies.

2153: Corporate procurements of renewable energy

Historical Data Methodology and Challenges:

Data was collected from the chart that is publicly available on Bloomberg Growing Corporate Presence in Power Markets Will Boost Clean Energy.

Corporate procurement departments are responsible for sourcing and purchasing a broad array of goods and services to meet the needs of the company, including securing its energy supply. To align with the net-zero agenda, renewable energy procurement is an essential part of corporate energy strategies. Because commercial energy consumption can represent a large proportion of global carbon emissions, such strategies could make a substantial contribution to decarbonization in certain countries.

There are four primary approaches to corporate renewable power purchasing. The options available to companies are often linked to the regulatory regime and rules in each country or jurisdiction where that company operates.

First, companies might consider using on-site power at their facilities — often called captive power or “behind the meter” power. Second, they might enter into direct power purchase agreements with developers. Third, companies might take advantage of specialized tariff programs offered by utilities to help expand renewables.

Fourth, in some cases, where renewable corporate energy procurement is not allowed or the company does not find another option, companies may use renewable energy certificates; this involves “matching” their demand in that location with a renewable energy certificate from another market. These activities require additional review and accounting to avoid double counting.

Just as renewable energy capacities have grown worldwide, so too have corporate procurements of renewable energy. In 2010, total corporate procurements stood at just 0.1 gigawatts (GW); by 2021, that figure had increased over 300 times to 31 GW.

Currently there is insufficient global data to relate renewable energy procurements to the total procurements of energy by corporate entities across these various purchasing approaches.

2154: Power sector emissions covered by carbon pricing

Historical Data Methodology and Challenges:

The World Bank Carbon Pricing Dashboard shows statistics of carbon pricing data, but currently it is not possible to differentiate carbon pricing schemes that cover the power sector specifically.

Carbon pricing generally can serve two purposes: incentivize climate change mitigation action, and shift the external costs of carbon dioxide (CO2) emissions back to the polluting source. Carbon prices send a negative economic signal to polluters to either reduce their emissions or pay a price.

Pricing mechanisms for carbon take many different shapes and forms in the power sector. Generally, they increase costs for highly polluting plants without impacting the economic performance of zero-carbon power generators.

Economists have long argued that carbon pricing is the most economically efficient mechanism to drive power sector decarbonization. This indicator seeks to quantify and track the share of power sector emissions that are covered by a carbon price; however, there is currently no reliable publicly available dataset on this indicator.

2155: Ratio of investment in renewables to fossil fuels

Historical Data Methodology and Challenges:

Data was calculated by dividing the renewable energy generation investment by investment in fossil fuel energy generation (including coal, oil and natural gas, and fossil fuel with CCUS).

Investments in renewable energy technologies have grown over the past decade. Finance committed to renewable energy projects grew from $343 billion in 2015 to $771 billion in 2023, predominantly directed toward solar photovoltaic (PV) and onshore wind projects. Meanwhile, the amount of investment in fossil fuels shrunk in that same time period.

One way to measure the scale of this shift is to track the ratio of investments in renewables as compared to that in fossil fuels.

In 2015 around twice as much investment was made in renewables than in fossil fuels. Preliminary estimates for 2024 expect there will be 10 times as much investment in renewables as in fossil fuels.

While market priorities are shifting decisively in the right direction, the amount of clean energy in the global power system needs to increase substantially by 2030 to align with the Paris Agreement.

2156: Organizations offering renewable energy training

Workers need new skills to perform jobs and activities necessary for future careers, like those related to renewable energy. The creation of opportunities for training and support is a crucial component of a just transition.

Employment opportunities and labor income are directly related to the skills and qualifications of workers. The acquisition of labor skills in renewable energies is essential to combat future employment challenges, especially as the world continues to shift away from fossil fuels in its efforts to reduce emissions.

A qualified labor force is key to achieving a growth in employment, labor productivity and real wages. Companies internalizing the costs of training demonstrate a desire to improve human capital, retain workers and increase global productivity.

There is currently no publicly available data on the percent of firms offering training and workshops in renewable energy skills.

2910: Jobs in renewable energy

The increasing number of jobs for men and women in renewable energy shows that greener energy can create decent and productive work opportunities. This is central to a just transition strategy.

The renewable energy jobs created must be quality jobs and accomplish basic rights. New employment opportunities should provide men and women with decent work, meaning that they should offer fair compensation, safe working conditions, equal opportunities and social protection. These jobs must be free of forced and child labor, and provide employees the right to organize or discuss work-related issues, among other conditions. The biofuels sector, which includes a significant portion of rural employment, is likely to suffer from decent work deficits.

Global employment in renewable energy was estimated at 16.2 million in 2023, up from 7.3 million in 2012 when it was first measured. Of the nearly 13 million jobs, the four largest employment sub-sectors within the renewable energy industry are solar photovoltaic (44%), bioenergy (24%), hydropower (14%) and wind energy (9%).

Meanwhile, women account for 32% of the global renewables workforce, but their participation varies widely among countries. Due to data and time limitations, we do not yet delve into the quality of these jobs, but this may be addressed in a future release of this platform.

1896: Investment in zero-carbon power systems

Historical Data Methodology and Challenges:

Total value accounts for investments in renewables generation, nuclear generation, storage and electricity networks.

The power sector emits 25% of global greenhouse gas emissions. Decarbonizing the sector requires massive investments into zero-carbon energy generation, particularly solar and wind, as well as auxiliary infrastructure such as energy storage, transmission and distribution lines.

Total investments in a zero-carbon power system, including zero-carbon generation, transmission, distribution and storage, grew from $724 billion in 2015 to $1.3 trillion in 2024. There has especially been an increase since 2021: Investments in renewables grew from $470 billion in 2021 to $771 billion in 2024, while investments in storage grew fivefold from $11 billion in 2021 to $54 billion in 2024. The Energy Transitions Commission estimates that $2.4 trillion in investments will be needed per year between now and 2050, with $1.3 trillion going to zero-carbon generation, $0.9 trillion going to transmission and distribution, and $0.2 trillion going to storage and flexibility.

1897: Cost of capital for renewable energy projects

Private investment in a company or project involves two types of parties: investors providing equity who bear more risk but expect higher returns, and lenders providing debt who bear lower risk but expect lower returns. The cost of capital reflects the perceived risk of investing in different technologies, and is affected by factors like regulatory regimes, economic conditions such as inflation or currency fluctuations, and the credit ratings of the utilities buying power from power projects. 

As financial institutions become more comfortable with low-carbon technologies, the cost of capital for related companies and projects declines. This makes it a crucial finance indicator to track how clean energy and other technologies in the low-carbon economy are attracting capital and scale.

Cost of capital is especially important for low-carbon technologies with high upfront costs, like renewable energy. Some factors can increase the cost of capital for all investments, and create disadvantages for these technologies that require higher upfront investments. Economic cycles may cause the cost of capital to increase over certain periods of time, for example, and developing markets have additional real and perceived risks that raise their cost of capital.  

The energy transition will accelerate in each market with access to cheap capital as the cost of financing zero-carbon technologies declines relative to high-carbon ones. The global average cost of capital for renewable energy (solar as well as onshore and offshore wind) has fallen steadily over the last decade and dropped from 7.6% in 2010 to 3.9 in 2022. In some countries, the cost of capital for a renewable power project is at the same rate or lower than its fossil fuel-powered equivalent. For example, in Brazil, the cost of capital for a gas-fired power plant in 2021 was 14-14.5%. The cost of capital for a solar plant in the same year was 12.5-13.5%.  

1898: Renewable energy permitting process duration

Renewable energy technologies, especially solar photovoltaic (PV) and wind, will make up the dominant portion of the energy mix in a Paris Agreement-aligned power sector. Achieving this will require building massive quantities of renewable energy projects at unprecedented pace and scale. 

Yet, the construction of renewable energy projects is being thwarted by existing permitting procedures in many parts of the world. For example, recent analysis shows it can take as long as ten years to obtain permits for onshore wind in Germany, while permissions for solar projects in the United States can require up to five years. As a result, many construction-ready renewable projects are currently blocked. Scaling up renewables at the pace necessary will not be possible if these lead times do not come down considerably. Countries need to urgently reform their permitting processes to enable faster deployment of renewable energy solutions.

The purpose of this indicator is to monitor the average time required to complete the permitting process for renewable energy projects country-by-country. Globally consistent data on this does not currently exist but would help measure the progress countries are making in reforming their regulatory systems. Ultimately, for a Paris Agreement-aligned energy transition, this indicator should be falling rapidly. 

Other shift Other shifts needed to transform the system

Phase out coal and unabated fossil gas electricity generation

Rapidly ending our current reliance on coal and fossil gas, relocating workers to new sectors, and eradicating public and private financing for fossil fuels will be critical to tackling the climate crisis.

Modernize power grids, scale energy storage and manage power demand

Scaling up efforts on power transmission and distribution, demand-side response and storage will require new policies to mobilize capital for new infrastructure; it will also create the market conditions for demand management programs and technological innovation.

Ensure energy access and a just and equitable transition for all

The transition of the world’s energy systems toward decarbonized, highly electrified models must benefit all people equitably.