The necessity of carbon removal in limiting global warming
Climate modeling scenarios indicate that even with deep emissions reductions, all pathways that limit warming to 1.5 degrees C (2.7 degrees F) include carbon dioxide removal — hereafter referred to as carbon removal or CDR. The amount of CDR ultimately needed depends on how much emissions are reduced in the near term: the more emissions are reduced in the short term, the less CDR will be necessary in the future to meet global climate goals.
A diverse suite of carbon removal approaches will be needed
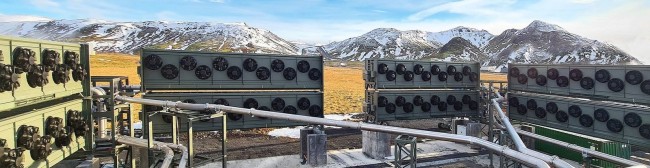
CDR can come from conventional or natural approaches like reforestation, but to effectively manage tradeoffs associated with each approach (including the saturation of natural sinks in the longer term, limited available land area and permanence), we need to develop a broad portfolio of approaches that also includes novel, or technological, CDR approaches.
Projecting the scale of carbon removal needed
Climate modeling scenarios show a wide range of reliance on CDR technologies, from less than one billion to more than five billion metric tons of removal annually by midcentury. Limiting future reliance on carbon removal to the lower end of this range will require greater focus on rapid near-term emissions reductions.
The role of stakeholders in scaling carbon removal
To reach gigatonne-scale CDR capacity, the public and private sectors and other stakeholders all have a role to play to increase funding for research, development and deployment of CDR technologies, expand enabling infrastructure, and develop robust governance structures that prioritize equity and sustainability.
The rapid growth and investment in carbon removal technologies
CDR has already made significant strides, transforming in less than a decade from a little-known concept to a well-defined need, with new technologies attracting billions of dollars in public and private financing. As the industry remains in early stages of development, there is an opportunity to help define standards and best practices for scaling up.
Discover what it would take to reach a positive tipping point for CDR, creating rapid and nonlinear growth that can help the world reach critical climate targets.